Commercial mortgages
Finance to buy, refinance, or release capital from commercial property. For the premises you trade from, and for property held as an investment.
Owning the premises, or holding the investment
A commercial mortgage is a loan secured against commercial property, repaid over the long term. There are two main routes, and they are judged differently.
Owner-occupier
Owner-occupier
Owner-occupier
Funds the premises your own business trades from. The lender looks first at the business: its trading record, its cash flow, and whether the profit comfortably covers the repayments. For many owners who have rented for years, buying is the point at which they stop paying someone else's mortgage and start building their own asset.
Investment
Owner-occupier
Owner-occupier
Funds property let to tenants. Here the lender looks at the rent and the strength of the tenant, and tests whether the income covers the payments with room to spare. The building, and the covenant behind it, matter as much as the borrower.
How much you can borrow
How much you can borrow depends on the property, the strength of the income behind it, and how the deal is put together. As a rule, an owner-occupier can borrow up to around 75 to 80% of the value, and an investment property up to around 70 to 75%, depending on the tenant.
There are ways to go further. Additional security, such as another property held outright, lets a lender advance more against the combined position. And professional practices, including dental, medical, veterinary and some legal and accountancy firms, can often borrow up to 100% of the value, because lenders treat that professional income as dependable.
Pricing is usually set as a margin over the Bank of England base rate, or as a fixed rate for a period. The strongest cases, a solid business buying at a sensible loan-to-value, are priced the keenest. Terms run up to 25 years, and a director's personal guarantee is normally part of the arrangement.
At a glance
Owner-occupier
Typically up to 75 to 80% of value
Investment
Typically up to 70 to 75%, depending on the tenant
Higher
With additional security, and up to 100% for professional practices
Term
Up to 25 years
Pricing
A margin over base rate, or a fixed rate
Security
The property, usually with a director's personal guarantee
The right lender, and the right structure
The commercial mortgage market is wide, and the difference between lenders is large. One will price an industrial unit keenly and shy away from retail. Another will lend against a specialist property that most will not touch. The same deal can look very different depending on who sees it.
We are whole-of-market, and after more than twenty years arranging commercial finance we know which lenders suit which properties and which businesses. We place your deal with the one likely to say yes on the best terms, rather than testing it against the whole market and hoping. And because every deal is led by a principal, you deal with the person structuring it, not a case handler you never meet.
We will also tell you when buying is not the right move, or when refinancing an existing facility would serve you better than a new purchase. The honest answer is the point.
How it works
It starts with the property and the numbers. We look at what you are buying or refinancing, and at the business or the rent that will support it, before approaching anyone. That tells us which lenders are realistic and what terms are achievable.
From there we structure the deal, place it with the right lender, and manage it through valuation and legal to completion. Property deals have moving parts, valuations, leases and searches among them, and keeping them moving is part of what we do.
In practice
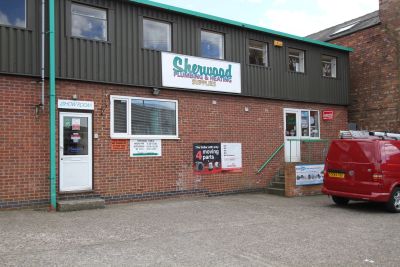
Sherwood Plumbing and Heating Supplies
Trade Supplies · £247,500 · Commercial Mortgage
A long-established plumbing and heating merchant wanted to buy the building it had traded from for years. We secured a 25-year commercial mortgage, fixed for the first 5 years so the business knows exactly what its repayments will be. No personal guarantees were required, and the business now owns its premises and has full control over its future.
"From the very beginning, the communication was outstanding. We were kept regularly updated at every stage of the process, and any questions or issues that arose were dealt with quickly and professionally. First class service!"
Ian Birkin, Partner
Talk to us about the property
Whether you are buying premises, refinancing a facility that is coming to an end, or weighing whether to buy at all, tell us about the property and the business behind it. We will tell you what is achievable.
Copyright - Goodman Corporate Consultancy Ltd
Goodman Corporate Finance is a trading style of Goodman Corporate Consultancy Ltd. Company no 5364029 Registered in England and Wales.
Registered office: 5 Prospect Place, Millennium Way, Pride Park, Derby, DE24 8HG.
Goodman Corporate Consultancy Limited is an FCA authorised Credit Broker and not a lender.
We typically receive a payment (s) or other benefits from the finance provider if you decide to enter into an agreement with them depending on the chosen provider and their commission or incentive models. Different lenders pay different amounts depending on different commission models. Further details of the commission model, calculation and amount will be disclosed to you throughout your customer journey.
Goodman Corporate Consultancy Ltd is Authorised and Regulated by the Financial Conduct Authority under number 733340.
Goodman Corporate Finance is registered with the ICO no. Z1828753.
Powered by GoDaddy